Last updated:
HMA Wealth may earn a commission if you sign up through some links on this page. This does not affect our recommendations. See our Disclaimer for details.
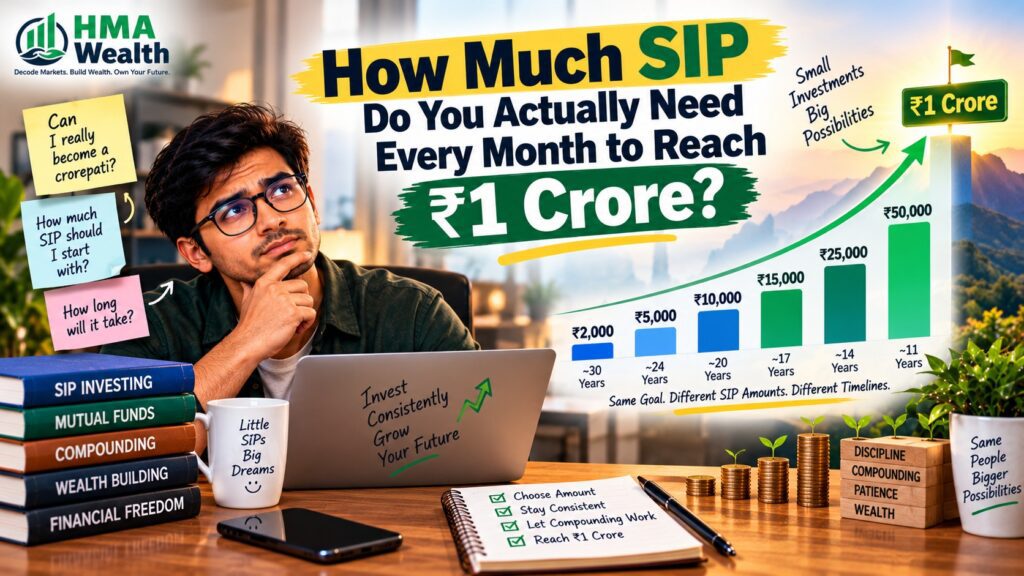
Table of Contents
A reader messaged HMA Wealth last month after seeing an Instagram reel that promised “just ₹5,000 a month makes you a crorepati.” He’d already set up the SIP before writing in, and only then asked the obvious question: over how many years, and at what return? The reel never said. That’s the problem with most how much SIP for 1 crore content floating around social media: it gives you a number without the two variables that actually decide it, your time horizon and your assumed rate of return.
Here’s the honest version. ₹5,000 a month can absolutely get you to ₹1 crore, but only over a long enough runway, roughly 26-27 years at a moderate 12% annual return. If you want to get there in 15 years instead, you’re looking at closer to ₹20,000 a month. Same destination, wildly different monthly commitment, depending entirely on how much time you give the money to compound.
What Does How Much SIP for 1 Crore Actually Depend On?
Before any single number means anything, three inputs decide it:
- Your investment horizon. How many years you’ll keep the SIP running without interruption.
- Your assumed rate of return. Typically modelled between 10% and 15% annually for equity-oriented mutual funds, though actual returns will vary year to year and can swing well outside that range.
- Whether your SIP stays flat or steps up. A fixed monthly amount versus one that increases a little each year as your income grows.
Change any one of these and the how much SIP for 1 crore answer changes with it. This is exactly why a generic “₹X a month makes you rich” claim, without stating the horizon and return assumption, isn’t really an answer at all.
How Much SIP Do You Need for ₹1 Crore Across Different Time Horizons?
Here’s the math worked out using the standard SIP future value formula, across a 10-30 year range and three illustrative return assumptions. These are illustrative figures only and not a promise of future returns, since actual mutual fund performance depends on market conditions and can land above or below any of these assumptions.
| Time Horizon | Monthly SIP at 10% p.a. | Monthly SIP at 12% p.a. | Monthly SIP at 15% p.a. |
|---|---|---|---|
| 10 years | ₹48,414 | ₹43,041 | ₹35,886 |
| 15 years | ₹23,928 | ₹19,819 | ₹14,774 |
| 20 years | ₹13,060 | ₹10,009 | ₹6,597 |
| 25 years | ₹7,474 | ₹5,270 | ₹3,045 |
| 30 years | ₹4,387 | ₹2,833 | ₹1,427 |
Notice how dramatically the required monthly SIP drops as the horizon stretches out. That’s compounding doing the heavy lifting rather than your monthly contribution, which is really the entire point of starting early. If you’re new to how this works mechanically, our explainer on what compounding actually means breaks down why those later years matter so much more than the early ones.
Why Does the Same ₹1 Crore Target Need Such Different SIP Amounts?
Because most of your eventual corpus isn’t money you put in, it’s growth on growth. Take the 20-year, 12% column: you’d invest roughly ₹24 lakh in total contributions (₹10,009 × 240 months) to reach a ₹1 crore corpus. The remaining ₹76 lakh is purely the return compounding on itself. Shorten that to 10 years at the same 12%, and your required monthly SIP more than quadruples, because you’re asking the same corpus to build in half the time with far less compounding runway behind it.
This is the real lesson buried inside these calculations: time in the market does more work than almost any other lever you control, including trying to chase a higher return by taking on more risk.
What If You Start a Step-Up SIP Instead of a Flat One?
A step-up SIP, where you increase your monthly investment by a fixed percentage every year, usually in line with a salary hike, changes the math substantially. Assuming a 10% annual step-up alongside a 12% return assumption:
| Time Horizon | Flat SIP for ₹1 Crore | Step-Up SIP (10% yearly increase) |
|---|---|---|
| 10 years | ₹43,041 | ₹29,932 |
| 15 years | ₹19,819 | ₹11,631 |
| 20 years | ₹10,009 | ₹5,078 |
A step-up approach can nearly halve your starting monthly SIP for the same 20-year target, since each year’s increase compounds alongside the market growth. The trade-off is discipline: you need to actually raise the SIP amount every year, which most people forget to do unless it’s automated through their platform.
Which Return Assumption Should You Actually Use?
This is where honesty matters more than optimism. Equity mutual fund category averages have historically landed in different ranges depending on the time period and category measured, and AMFI publishes category-wise fund performance data that’s worth checking before you lock in an assumption for your own plan. SEBI’s investor education portal is also a reliable place to understand how mutual fund risk and return actually work before you commit to a long-term number.
A conservative planner often works with 10-12% for a diversified equity portfolio over a long horizon, reserving 15% for best-case scenarios rather than a baseline expectation. Using an overly optimistic number is one of the most common ways people under-save for a goal they think they’ve already solved for.
If you haven’t picked funds yet, our guide on mutual funds for beginners is a reasonable starting point before you commit a number to any SIP.
How Does Inflation Change What ₹1 Crore Is Actually Worth?
This is the part most SIP calculators conveniently skip. ₹1 crore today and ₹1 crore in 20 years are not the same amount of real purchasing power. At a moderate 6% average inflation rate, ₹1 crore 20 years from now would have roughly the buying power of ₹31 lakh today, which is a sobering number if your entire plan was built around “reaching a crore” rather than what that crore can actually buy.
The practical fix isn’t complicated: either target a larger corpus upfront to account for inflation, or treat ₹1 crore as a milestone within a bigger plan rather than the finish line itself. If your actual goal is retirement or a child’s education 20-25 years out, it’s worth running the numbers with your real future cost in mind, not today’s price tag. A financial planner, or even a basic spreadsheet model, can help translate today’s ₹1 crore goal into tomorrow’s inflation-adjusted equivalent.
How Does a Lump Sum Combined With SIP Change the Picture?
Few people start a SIP from zero. If you already have savings sitting in a fixed deposit or a savings account, combining a lump sum investment with your monthly SIP can meaningfully cut down the monthly amount you’d otherwise need. For instance, a ₹5 lakh lump sum invested today, left to grow at 12% annually for 15 years, would itself grow to roughly ₹27.4 lakh, reducing the gap your SIP needs to close for the same ₹1 crore target.
This is particularly relevant if you’ve received a bonus, an inheritance, or matured an old insurance policy and are deciding what to do with it. Rather than letting it sit idle or splitting it across too many products, directing a portion toward the same goal as your SIP lets both pieces compound together instead of working in isolation.
What Mistakes Derail People Chasing a ₹1 Crore SIP Target?
- Picking a return assumption that’s too optimistic, which understates how much SIP for 1 crore you actually need and leaves you short at the finish line
- Stopping the SIP during a market fall, which locks in losses and breaks the compounding chain exactly when units are cheapest to buy
- Never increasing the SIP amount even as income grows, leaving a flat SIP to do all the work a step-up SIP could have shared
- Treating the ₹1 crore number as fixed, without adjusting for inflation eroding its real purchasing power by the time you reach it
- Redeeming early for a non-emergency, which resets the compounding clock and usually costs far more than whatever the withdrawal was for
Does the Fund You Choose Change How Much SIP You Need?
Yes, indirectly. The numbers above assume a steady average return, but your actual fund’s category (large-cap, flexi-cap, mid-cap, or a mix) and its expense ratio both influence the real return you receive. A higher expense ratio eats into your net return every single year, which compounds against you the same way a good return compounds in your favour. It’s worth comparing a fund’s direct plan (lower expense ratio, no distributor commission) against its regular plan on platforms like Zerodha Coin, Groww, or INDmoney before committing a long-term SIP.
Does It Matter Which Platform You Run the SIP Through?
Not for the underlying math, but it matters for the habit. The required monthly figure stays the same whether you invest through a bank’s mutual fund portal, a direct platform like Zerodha Coin or Groww, or an app like INDmoney that also tracks your other holdings alongside it. What actually changes outcomes is friction: a platform where starting, pausing, and stepping up your SIP takes thirty seconds is one you’re far more likely to stick with for 15-20 years than one that makes every change a hassle.
It’s also worth setting up auto-debit rather than manual monthly transfers. A SIP that depends on you remembering to invest every month is a SIP that quietly stops the first time life gets busy, and those gaps compound against you just as surely as a missed EMI does. Most platforms also let you set an auto step-up at the time of registration itself, so the yearly increase happens without a single extra action on your part once it’s configured.
How Do You Actually Start This Without Overcomplicating It?
- Decide your real time horizon first. Ten years looks nothing like thirty on this chart, so this single decision shapes everything else.
- Pick a conservative return assumption, ideally 10-12%, and plan around it rather than the best-case number.
- Run your own numbers on the HMA Wealth SIP Calculator using your specific horizon and target, rather than relying on a generic table.
- Automate a yearly step-up, even a modest 5-10%, so your SIP grows with your income without you having to remember.
- Review once a year, not once a week. Checking a long-horizon SIP daily tends to trigger exactly the panic-driven decisions that derail the plan.
HMA Wealth exists to turn exactly this kind of back-of-the-envelope math into something you can actually act on, grounded in real SIP mechanics rather than a reel promising a number with no context behind it.
Mutual fund investments are subject to market risks; read all scheme-related documents carefully before investing. This article is educational content meant to help you understand how much SIP for 1 crore realistically requires, not personalised investment advice. Your own ideal SIP amount depends on your income, goals, and risk appetite, so for decisions specific to your situation, it’s worth consulting a SEBI-registered investment adviser. Return assumptions used here are illustrative only, not a promise of what any fund will deliver, and actual fund performance should always be checked against current data from AMFI before you commit to a number.
At the end of the day, the real answer to how much SIP for 1 crore isn’t one figure, it’s whichever row on that table matches the number of years you’re actually willing to give it, and the earlier you start, the smaller that monthly number gets.
The reader who wrote in after that Instagram reel eventually settled on a 15-year horizon with a modest step-up built in, rather than chasing the flashier 10-year number the reel implied. That’s really the quiet truth behind most of these calculations: the “right” answer isn’t the smallest possible monthly figure, it’s the one you can realistically sustain, year after year, without a single skipped month breaking the compounding chain you’re counting on.
FAQs — How Much SIP Do You Actually Need Every Month to Reach ₹1 Crore?
How much SIP for 1 crore in 15 years?
At a 12% illustrative annual return, how much SIP for 1 crore in 15 years works out to roughly ₹19,800 a month. At a more conservative 10%, it rises to about ₹23,900. Actual returns vary, so treat these as planning estimates rather than a fixed outcome.
How much SIP for 1 crore in 20 years?
Stretching the horizon to 20 years drops the required amount significantly, to around ₹10,000 a month at a 12% illustrative return. This is the core answer to how much SIP for 1 crore questions: more time sharply reduces the monthly commitment needed.
Is ₹5,000 SIP enough to reach 1 crore?
Yes, but only over a long horizon. A flat ₹5,000 monthly SIP needs roughly 26-27 years at a 12% illustrative return to reach ₹1 crore. Starting a step-up SIP instead, increasing the amount yearly, can shorten how much SIP for 1 crore timelines considerably.
Does a step-up SIP change how much SIP for 1 crore I need?
Yes, significantly. A 10% yearly step-up on a 20-year horizon can nearly halve how much SIP for 1 crore you’d need compared to a flat amount, since each year’s increase compounds alongside market growth. It does require actively raising the SIP amount every year, ideally automated.
What return rate should I use to calculate how much SIP for 1 crore I need?
A conservative 10-12% annual return is the reasonable assumption most planners use when working out how much SIP for 1 crore requires for a diversified equity portfolio. Reserve 15% for best-case scenarios only, since actual fund performance depends on market conditions.