Last updated:
HMA Wealth may earn a commission if you sign up through some links on this page. This does not affect our recommendations. See our Disclaimer for details.
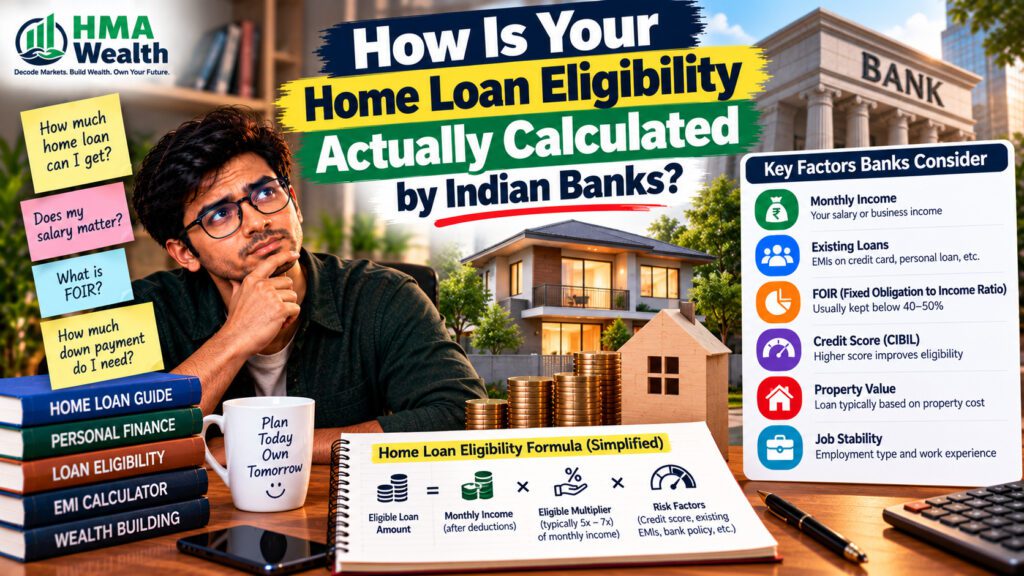
Table of Contents
A reader wrote to HMA Wealth convinced his bank had made an error. He earned ₹80,000 a month, had a clean repayment history, and expected an eligibility figure north of ₹50 lakh. The bank offered him ₹28 lakh. Nothing was wrong on the bank’s end; he simply didn’t know that a ₹15,000 car EMI he’d nearly forgotten about was quietly eating into the number before the calculation even started. Every home loan eligibility calculator India banks use runs on the same handful of inputs, and once you understand what they actually are, that kind of surprise stops happening.
What Is FOIR, and Why Does It Decide Almost Everything?
At HMA Wealth, we get versions of that reader’s question almost every week, usually from someone staring at a sanction letter that doesn’t match the number they’d mentally budgeted for. Fixed Obligation to Income Ratio (FOIR) is the single biggest lever behind every home loan eligibility calculator India lenders rely on. It measures what share of your gross monthly income is already committed to fixed obligations, existing EMIs, insurance premiums, and rent, before a new loan EMI even enters the picture.
FOIR = (Total fixed monthly obligations ÷ Gross monthly income) × 100
Most lenders work with an ideal FOIR of 40-50%, meaning they’re generally comfortable letting your total fixed obligations, including the new home loan EMI, consume up to that share of your gross income. Higher earners sometimes get a little more room; applicants with lower or less stable income typically face a stricter cap. Checking where you currently stand matters here; our guide on how to check your credit score is a reasonable first stop before you start running numbers, since your credit profile and your FOIR get assessed together.
How Does the Calculation Actually Work Behind the Scenes?
Once a lender has your FOIR-based EMI capacity, they work backward using the standard loan amortisation formula to arrive at a maximum loan amount, based on the prevailing interest rate and your chosen tenure. Here’s an illustrative example at a 50% FOIR, an 8.75% interest rate, and a 20-year tenure:
| Monthly Salary | Max EMI (50% FOIR) | Illustrative Loan Eligibility |
|---|---|---|
| ₹40,000 | ₹20,000 | ₹22.6 lakh |
| ₹60,000 | ₹30,000 | ₹33.9 lakh |
| ₹80,000 | ₹40,000 | ₹45.3 lakh |
| ₹1,00,000 | ₹50,000 | ₹56.6 lakh |
| ₹1,50,000 | ₹75,000 | ₹84.9 lakh |
These figures are illustrative only, calculated using a standard EMI formula at one indicative rate and tenure; your actual eligibility will vary by lender policy, your specific interest rate, and your full financial profile. Since home loan interest rates in India are linked to the RBI’s external benchmark lending rate framework, the exact rate your bank offers shifts with monetary policy, so always run a current online home loan eligibility calculator India banks publish on their own sites rather than treating any table as fixed.
How Much Does an Existing EMI Quietly Shrink Your Eligibility?
This is exactly what happened to the reader from the intro. At ₹80,000 salary and 50% FOIR, his total EMI capacity was ₹40,000. A forgotten ₹15,000 car EMI left only ₹25,000 available for the new home loan, dropping his eligibility from roughly ₹45.3 lakh to about ₹28.3 lakh, nearly a 38% cut from one existing obligation he’d mentally written off. If you’re carrying a personal loan or credit card EMI alongside a car loan, our comparison of personal loans versus credit cards is worth a look before you assume your existing debt load is negligible.
This is also why clearing small, high-interest debts before applying is one of the most effective things you can do. Our guide on how to improve your credit score fast covers several of the same moves that free up FOIR headroom at the same time.
Does a Longer Tenure Genuinely Increase What You Can Borrow?
Yes, noticeably, because a longer tenure lowers your monthly EMI for the same loan amount, which stretches your fixed FOIR capacity further. At a ₹40,000 monthly EMI cap and the same 8.75% rate, eligibility looks like this across different tenures:
| Tenure | Illustrative Loan Eligibility |
|---|---|
| 10 years | ₹31.9 lakh |
| 15 years | ₹40.0 lakh |
| 20 years | ₹45.3 lakh |
| 30 years | ₹50.8 lakh |
A longer tenure genuinely raises what a home loan eligibility calculator India lenders use will show you, but it also means paying considerably more total interest over the life of the loan. If you’re weighing whether to stretch the tenure or prepay aggressively later, stockcharcha.in’s loan-vs-invest calculator is a useful way to see whether prepaying or investing the difference actually serves you better over time.
How Much Does Your CIBIL Score Change the Number?
Significantly, and not just on the interest rate you’re offered. A strong score, generally 750 and above, signals low risk and can push a lender toward the more generous end of their FOIR band, while a weak or thin credit file can mean a stricter cap, a lower loan-to-value ratio, or a flat rejection regardless of income. CIBIL itself notes that the closer your score sits to 900, the better your approval odds across any credit product, home loans included. Our deeper dive on what counts as a good CIBIL score breaks this down further if you want the full picture before applying.
If anything on your report looks off, a wrongly marked late payment can suppress your score and your eligibility together, so it’s worth checking our walkthrough on fixing errors in your credit report before a big application rather than after a rejection.
Does Adding a Co-Applicant Genuinely Boost Eligibility?
Yes, often substantially. Most banks will combine the incomes of co-applicants (typically a spouse or parent with a steady income) when calculating FOIR, which directly raises the EMI capacity and therefore the loan amount a home loan eligibility calculator India banks use will return. This is one of the most reliable ways to close a meaningful eligibility gap without waiting years for an income increase, provided the co-applicant’s own existing obligations don’t offset the benefit.
Do Self-Employed Applicants Get Calculated Differently?
Yes, and this trips up a lot of business owners and freelancers who assume the process is identical to a salaried applicant’s. Rather than a single salary slip, lenders typically average your income across the last 2-3 years of Income Tax Returns filed with the Income Tax Department, which means your declared taxable income, not your gross business turnover, is usually what feeds the FOIR calculation. Filing accurate, complete returns matters more here than almost anywhere else in personal finance; our guide on how to file your ITR online in India is worth revisiting if your filings have been inconsistent in recent years, since gaps or under-reported income can meaningfully shrink what you’re eligible to borrow.
Does the Property Itself Affect Your Eligibility, Not Just Your Income?
Yes, through the Loan-to-Value (LTV) ratio, which caps how much of the property’s assessed value a bank will finance, typically 75-90% depending on the loan amount, regardless of how strong your income-based eligibility looks. Even if your FOIR comfortably supports a ₹60 lakh loan, a bank won’t lend more than the LTV-permitted share of the actual property’s value, so your final sanctioned amount is effectively the lower of your income-based eligibility and the property-based LTV cap. This distinction matters more for a commercial purchase than a residential one, since LTV norms and risk weighting differ between the two; our comparison of commercial versus residential property is worth reading if you’re weighing either option.
How Does Your Tax Regime Choice Affect the Numbers Lenders See?
This is a detail that surprises a lot of applicants, particularly the self-employed. Since lenders often work from your declared taxable income on your ITR rather than your gross earnings, your choice between the new and old tax regime can subtly shift what shows up as “income” for eligibility purposes, depending on which deductions you’ve claimed and how they affect your reported taxable figure. Our comparison of the new tax regime versus the old tax regime is worth understanding well before a home loan application season, not just at tax filing time, since the regime you pick has knock-on effects beyond just your tax bill.
What Documents Does the Bank Actually Use to Verify This Number?
- Income proof: salary slips and Form 16 for salaried applicants, or 2-3 years of ITRs and bank statements for self-employed applicants
- Existing loan statements: to verify your current EMI obligations against what’s showing on your credit report
- Bank statements: typically the last 6 months, to cross-check declared income and spot undisclosed obligations
- Identity and address proof: PAN, Aadhaar, and standard KYC documents, verified under RBI’s KYC norms that apply uniformly across banks and housing finance companies
- Your credit report itself: lenders pull this directly from CIBIL rather than relying on the score you report, so it’s worth having your own current copy in hand to cross-check
- Property documents: once you’ve identified a specific property, since the loan-to-value ratio is assessed against the property’s value too, not income alone
What Mistakes Shrink Your Eligibility Without People Realising?
- Forgetting a small existing EMI, exactly like the reader from the intro, which can cut eligibility by a third or more
- Applying before checking your credit report, missing an error that’s artificially suppressing your score
- Not accounting for upcoming big-ticket obligations, like a new car loan applied for around the same time, which lenders will factor in if it shows on your credit report
- Assuming gross income is what counts, when self-employed applicants are actually assessed on declared taxable income after deductions
- Skipping the co-applicant option, when adding a spouse or parent’s income could have closed the gap entirely
If debt management generally feels unclear, our explainer on the 50/30/20 budgeting rule is a useful framework for understanding how much of your income should realistically go toward fixed obligations like a future home loan EMI in the first place. Building that habit well before you apply, using a structured approach like our guide on creating a monthly budget, also makes it far easier to spot a forgotten EMI or an underused credit line before a bank’s FOIR calculation does it for you.
It’s also worth knowing your alternatives if a FOIR shortfall leaves you short of what you need. A gold loan or a personal loan for the gap isn’t usually the cheapest route, since both typically carry higher rates than a secured home loan, but understanding the trade-off helps you decide whether to bridge a small shortfall or simply wait and reapply once your FOIR improves.
How Do You Use an Online Calculator Correctly Before Applying?
- Gather your real numbers first: gross monthly income, every existing EMI (even small ones), and your current credit score.
- Run the numbers through your bank’s own home loan eligibility calculator India-specific lenders publish on their websites, rather than a generic third-party tool, since FOIR bands vary by lender.
- Test it with and without a co-applicant to see the actual difference, not just a theoretical one.
- Check your credit report for errors first, since a wrongly reported default can distort every subsequent number.
- Compare tenure options, understanding that a longer tenure raises eligibility but increases total interest paid.
- Treat the output as a starting estimate, not a fixed sanction amount, since the bank’s final underwriting also weighs the specific property, your employment stability, and other policy-specific factors.
HMA Wealth built this breakdown because most people only learn how FOIR actually works after a disappointing eligibility figure, not before, and the gap between expectation and reality is almost always explained by one or two inputs people simply weren’t accounting for.
This article is educational content meant to help you understand how a home loan eligibility calculator India banks use actually works, not personalised financial advice. Housing finance companies and banks are regulated separately by the Reserve Bank of India and the National Housing Bank, and specific eligibility criteria, FOIR bands, and interest rates vary by lender and change periodically, so always verify current figures directly with your bank or CIBIL before applying, and consult a SEBI-registered investment adviser for decisions specific to your broader financial situation. If you’re also weighing whether a home loan fits into your larger financial picture, stockcharcha.in’s loan-vs-invest calculator is a useful companion tool once you have an eligibility figure in hand.
At the end of the day, a home loan eligibility calculator India banks offer isn’t guessing; it’s running your real numbers through a formula you can now see clearly for yourself. The surprise your bank’s number gives you is usually just one overlooked EMI or one unchecked credit report away from making perfect sense.
FAQs — How Is Your Home Loan Eligibility Actually Calculated by Indian Banks?
What is a home loan eligibility calculator India banks actually use based on?
It’s based on your FOIR (Fixed Obligation to Income Ratio), which compares your fixed monthly obligations, including the new EMI, against your gross income, usually within a 40-50% band.
How do existing EMIs affect a home loan eligibility calculator India lenders apply?
Any existing EMI reduces the fixed-obligation headroom available for the new loan, which can cut your eligibility by a third or more depending on the obligation’s size relative to your income.
Does a home loan eligibility calculator India offers change with tenure?
Yes. A longer tenure lowers the monthly EMI for the same loan amount, which raises the eligibility figure, though it also increases total interest paid over the loan’s life.
Can a co-applicant improve results from a home loan eligibility calculator India banks use?
Yes, usually substantially. Combining a co-applicant’s income with yours raises the total EMI capacity banks factor into the calculation, directly increasing the loan amount you qualify for.
Is a home loan eligibility calculator India shows online always accurate?
It’s a reliable starting estimate, not a fixed sanction figure, since final underwriting also weighs the specific property, your employment stability, and lender-specific policy factors beyond the basic FOIR math.