Last updated:
HMA Wealth may earn a commission if you sign up through some links on this page. This does not affect our recommendations. See our Disclaimer for details.
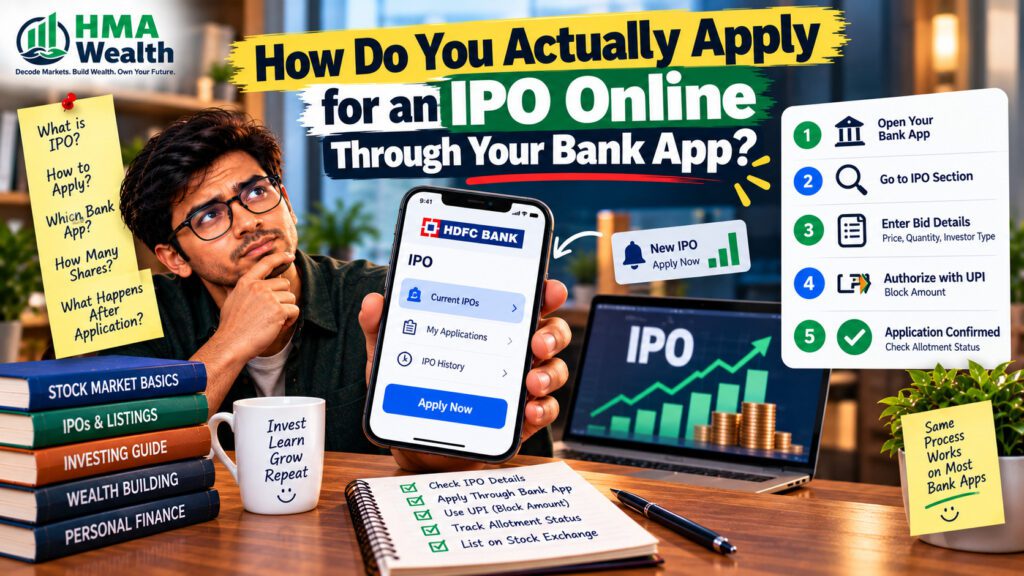
Table of Contents
HMA Wealth’s founder still remembers his first attempt at applying for an IPO through his bank’s net banking portal, back when he assumed it would work like any other online payment. It didn’t. He entered the wrong bid price, missed the UPI mandate approval window by a few hours, and watched his application get auto-rejected without ever actually blocking his money. That one mistake is exactly why most people searching how to apply for IPO online end up more confused after reading a generic guide than before, because the process has a few specific steps that genuinely trip people up if you don’t know them in advance.
What Do You Need Ready Before You Even Open Your Bank App?
Before you touch the IPO section of your app, have these four things confirmed:
- A Demat account linked to the same bank or broker, since shares are credited electronically and can’t be applied for without one. If you don’t have one yet, our explainer on what a demat account actually is covers how to open one first.
- Your PAN, matching exactly what’s registered on your Demat account. A mismatch is one of the most common reasons an application gets silently rejected.
- A UPI ID registered with an app like Google Pay, PhonePe, or BHIM, if you’re applying through the UPI route rather than pure ASBA.
- Sufficient balance in your linked bank account to cover the full bid amount, since the entire amount gets blocked upfront, not charged in instalments.
How Do You Actually Apply for an IPO Online Through Your Bank App?
Most major Indian banks (SBI YONO, HDFC, ICICI iMobile, Axis, and others) now have an IPO or “e-Services” section built directly into their net banking or mobile app. The process via ASBA (Applications Supported by Blocked Amount) generally looks like this:
- Log in to your bank’s net banking portal or mobile app and locate the IPO or e-Services section, usually under “Investments” or “Demat Services.”
- Select the live IPO you want to apply for from the list of currently open issues.
- Choose your lot size. Shares are sold in fixed lots, not individual units, so you’re selecting a multiple of the minimum lot rather than an exact share count.
- Bid at the cut-off price, unless you have a specific reason to bid lower. Bidding below the eventual issue price is one of the most common ways a first-time application gets rejected outright.
- Enter your Demat account number so the bank knows where to credit shares if you’re allotted.
- Confirm the application. Your bank automatically blocks the required amount in your account, rather than debiting it immediately.
This is the core of how to apply for IPO online through most Indian bank apps today, and it’s genuinely a 5-10 minute process once you know where the section lives.
What’s the UPI Route, and How Is It Different from Pure ASBA?
If you’re applying through a broker app (like Zerodha, Groww, or INDmoney) rather than your bank’s own portal, you’ll typically use the UPI-ASBA hybrid route instead. The steps shift slightly: you select the IPO and lot size in the broker app, enter your UPI ID, and then approve a mandate request that arrives in your UPI app. The underlying mechanism is identical to pure ASBA, your bank still blocks the funds rather than debiting them, but the application interface sits with your broker rather than your bank.
Either path answers how to apply for IPO online correctly; the choice mostly comes down to which app you already use for investing and how comfortable you are with each platform’s interface.
What Happens to Your Money After You Apply?
This is the part that worries first-time applicants the most. Your bid amount is frozen in your bank account, not withdrawn. It continues earning the usual interest on your savings or current account balance while blocked. If you’re allotted shares, the exact amount is debited at that point. If you’re not allotted, or only partially allotted, the unused portion is released back to you automatically, with no manual request needed on your part.
What’s the Real Timeline From Application to Listing?
Since SEBI shortened the IPO listing cycle, the gap between the issue closing and shares hitting the exchange has become considerably tighter than it used to be:
| Day | What Happens |
|---|---|
| T (closing day) | The IPO window closes to new applications |
| T+1 | Allotment is finalised and basis of allotment is published |
| T+2 | Unsuccessful or partial bids are unblocked, and allotted shares are credited to Demat accounts |
| T+3 | Shares list and begin trading on NSE and BSE |
This timeline can shift slightly around holidays or depending on the specific issue, so always check the current schedule on NSE’s official IPO page or your bank’s IPO section before assuming these exact dates for a live issue. This compressed cycle is a genuine improvement for applicants, since your blocked money is freed up, one way or another, within days rather than the roughly week-long wait that older IPO cycles used to involve.
How Much Can You Actually Apply For as a Retail Investor?
The Retail Individual Investor (RII) category, which gets a reserved portion of most IPOs and typically better allotment odds relative to the number of applicants, covers applications up to ₹2 lakh. Applying for a larger amount moves you into the Non-Institutional Investor (NII) category instead, which has different allotment dynamics and no reserved quota in the same way. SEBI’s investor education portal is worth checking for the current category thresholds before a large application, since these figures are set by regulation and can be revised.
Can You Modify or Cancel Your Bid After Submitting It?
Yes, within limits. Most bank apps and broker platforms allow you to revise your bid quantity or price while the IPO window is still open, usually through the same IPO or e-Services section where you applied. You generally can’t revise it downward below the minimum lot size, and once the issue closes, no further changes are possible regardless of the platform. Cancelling the application entirely, rather than modifying it, releases the blocked amount back to you, though this should happen automatically anyway once the window closes if you’re not allotted shares.
If you realise you’ve entered the wrong lot size or bid price shortly after submitting, check this revision option before assuming you’re stuck with the mistake. It’s a genuinely useful safety net that a lot of first-time applicants don’t know exists.
Does Applying Through a Broker App Change Your Allotment Odds?
No, and this is worth clarifying because it’s a common misconception. Whether you apply through your bank’s net banking portal, a broker’s UPI-ASBA flow, or a different broker entirely, your application enters the same registrar’s pool for that specific investor category. The registrar, not your bank or broker, runs the allotment process, typically through a computerised lottery system when an issue is oversubscribed in the retail category. The platform you use affects your experience of applying, not your statistical chances of being allotted shares.
What can genuinely improve your odds, within the retail category, is applying through multiple eligible family members’ PANs (each with their own Demat account), since each valid application gets its own shot in the lottery. This is a legitimate, commonly used approach, distinct from the prohibited practice of one person submitting multiple applications under their own PAN. Keep each family member’s bank account, PAN, and Demat account consistent with each other when doing this, since a mismatch across any of the three is just as likely to cause a rejection as any other data-entry error on the form.
What Mistakes Derail a First-Time Application?
- Missing the UPI mandate approval window. Most banks require approval of the block request well before the issue closes, often by a specific cut-off time on the final day, and a late approval gets auto-rejected with no exceptions.
- Bidding below the cut-off price without understanding this sharply reduces, or eliminates, your allotment chances.
- Applying multiple times under the same PAN, which most issues disallow and which can get both applications rejected rather than just the duplicate.
- Not keeping sufficient balance in the linked account for the full blocking amount, which causes the mandate approval itself to fail.
- Confusing “blocked” with “deducted” and panicking when the balance shows as unavailable, when nothing has actually been spent yet.
What If Your UPI Mandate Doesn’t Arrive or You Miss the Window?
If the mandate notification doesn’t show up in your UPI app within a reasonable time, check that your UPI ID is correctly linked to the same bank account you intend to use, and that your UPI app’s notifications aren’t being blocked by your phone’s settings. It’s also worth checking that your UPI app itself is updated to the latest version, since an outdated app occasionally fails to display mandate requests correctly even when the request has technically gone through. If you do miss the approval deadline, there’s no workaround; the application is auto-rejected, and you’d need to reapply before the issue closes if there’s still time, or try the pure ASBA route through your bank’s portal instead, which doesn’t depend on a UPI mandate at all.
Does It Matter Which Bank App You Use?
Not for the underlying mechanics, but interface quality varies noticeably between banks, and a clunky app is a common reason people give up partway through. If your primary bank’s app makes the IPO section hard to find, applying through a broker’s UPI-ASBA flow instead is often the smoother version of how to apply for IPO online, since most dedicated investing apps are built specifically around this one task rather than burying it inside a general-purpose banking app.
Once you’ve got the mechanics down, it’s worth reading our broader guide on what an IPO actually is before committing real money to a specific issue, since knowing how to apply is only half the decision; whether that particular IPO is worth applying for is the other half entirely. If IPO investing is your first step into equities altogether, our guide on how to start investing covers the broader groundwork worth having in place first.
HMA Wealth put together this walkthrough because the application process itself, not the investment decision, is where most first-time applicants actually get stuck, and a rejected application due to a missed deadline or a bidding error is a frustrating way to lose out on an opportunity you were otherwise ready for.
This article is educational content meant to help you understand how to apply for IPO online correctly, not personalised investment advice. Whether any specific IPO is worth applying for depends on factors beyond the application process itself, so for decisions about individual issues, it’s worth consulting a SEBI-registered investment adviser and reading the issue’s official offer document. IPO application processes, deadlines, and investor category limits are set by SEBI and can be revised, so always verify current rules before applying to a live issue.
At the end of the day, how to apply for IPO online isn’t complicated once you’ve done it correctly once. It’s getting the bid price, the mandate timing, and the account balance right on the first attempt that trips up most new applicants, and now you know exactly where those three things tend to go wrong.
HMA Wealth’s founder eventually did get allotted shares in a later IPO, once he’d learned to bid at cut-off, keep his phone’s notifications on, and approve the mandate the moment it arrived rather than putting it off until later in the day. None of that required any special insight, just knowing the three specific points where a first attempt usually goes wrong, which is really the entire purpose of a walkthrough like this one.
FAQs — How Do You Actually Apply for an IPO Online Through Your Bank App?
How to apply for IPO online through my bank’s net banking?
Log in to your bank’s app, find the IPO or e-Services section, select the issue, choose your lot size, bid at cut-off, and enter your Demat account number. This ASBA route is the most direct way for how to apply for IPO online without a separate broker app.
How to apply for IPO online using UPI instead of ASBA?
Through a broker app like Zerodha or Groww, select the IPO and lot size, enter your UPI ID, then approve the mandate in your UPI app. It’s the same mechanism as how to apply for IPO online via your bank, just with the interface sitting with your broker.
Does my money get deducted immediately when I apply for an IPO?
No. The bid amount is blocked, not debited, and continues earning interest while frozen. This is a core part of how to apply for IPO online safely, since the money is only deducted if you’re actually allotted shares, and released automatically otherwise.
What’s the deadline for approving the UPI mandate?
Most banks require approval before a specific cut-off time on the day the issue closes, and a late approval is auto-rejected with no exceptions. Knowing this deadline is essential to how to apply for IPO online successfully through the UPI route.
How much can I apply for as a retail investor?
The Retail Individual Investor category covers applications up to ₹2 lakh, with its own reserved allotment quota. This limit shapes how to apply for IPO online within the retail bracket versus moving into the Non-Institutional Investor category for larger amounts.