Last updated:
HMA Wealth may earn a commission if you sign up through some links on this page. This does not affect our recommendations. See our Disclaimer for details.
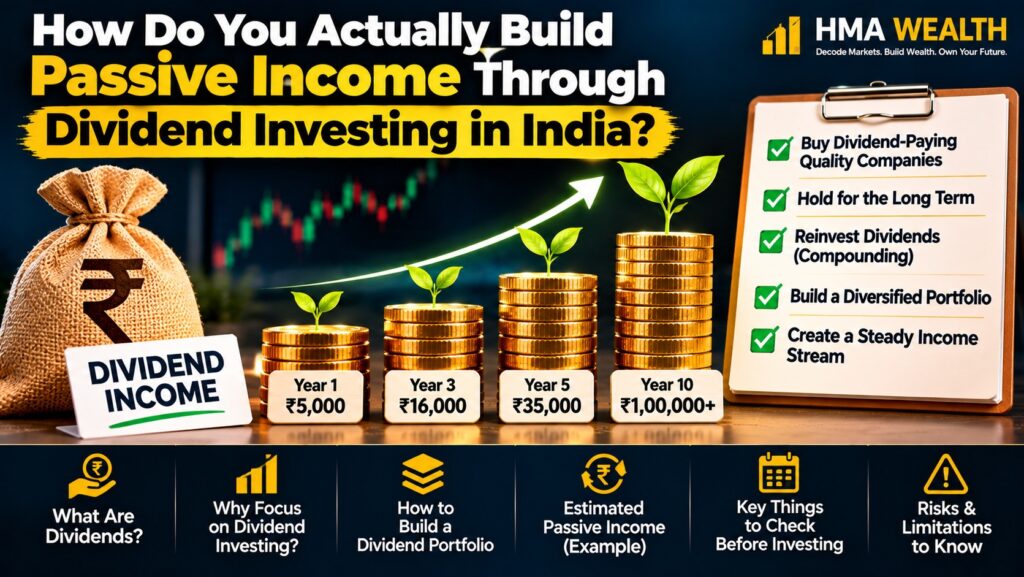
Table of Contents
The first dividend I ever got credited to my bank account was ₹340. I remember because I’d just bought 50 shares of a PSU company after reading a forum post about “dividend kings,” and I genuinely expected something more dramatic to show up in my account. It didn’t. It took me another two years of actually tracking my payouts in a spreadsheet to realise dividend investing for passive income isn’t a get-rich scheme at all, it’s a slow accumulation game that only starts looking like real income once your capital base is large enough.
That gap between expectation and reality is exactly where most people give up on dividend investing for passive income too early, usually within the first year, right when the compounding hasn’t had time to do anything visible yet. Anyone weighing dividend investing for passive income against simpler growth investing is really asking the same underlying question most new investors eventually face: income now versus a bigger number later. This is the kind of practical, lived-through gap HMA Wealth exists to close for readers, not another listicle of “top 10 dividend stocks,” but an honest walkthrough of what actually builds income over years, not months. If you haven’t set up your first investment account yet, our guide on how to start investing is worth reading before any of this.
Why Did I Start Looking at Dividend Investing for Passive Income in the First Place?
Our own habit-building guide on the pay-yourself-first approach is where this instinct actually started for me, treating investing as a fixed monthly commitment rather than whatever was left over. I was tired of watching my entire portfolio’s value depend on share price alone. A stock could be up 40% on paper, but unless I sold it, that gain meant nothing I could actually spend. Dividends felt different, cash that landed in my account whether I sold anything or not, which is the entire appeal of dividend investing for passive income as a strategy.
It also appealed to a part of me that wanted to stop checking stock prices every day. What is a dividend, in the simplest sense, is a portion of a company’s profit paid out to shareholders, usually once or twice a year, and that payout doesn’t ask you to do anything once you own the shares.
What Exactly Counts as Dividend Investing for Passive Income?
It’s narrower than people assume. Buying a stock that pays dividends occasionally doesn’t make you a dividend investor, it’s buying companies with a consistent, multi-year track record of paying and ideally growing their dividend, and holding them specifically for that income stream rather than for price appreciation.
This distinction matters because a lot of high-growth companies pay no dividend at all, reinvesting every rupee of profit into growth instead. Our explainer on common investing mistakes covers this confusion, people chasing a stock’s dividend yield without checking whether the company can actually sustain that payout.
How Much Capital Do You Actually Need to Generate Meaningful Dividend Income?
This is the number nobody wants to say out loud, because it’s humbling. At a realistic average dividend yield of 3-4% across a diversified basket of Indian dividend-paying stocks, you’d need roughly ₹25-30 lakh invested to generate about ₹1 lakh a year in dividend income, before tax. If that number feels far off right now, our mutual funds for beginners guide is a reasonable place to build the base habit before shifting any of it toward a dividend-specific sleeve later.
| Invested amount | Approx. yearly dividend at 3.5% yield (illustrative) |
|---|---|
| ₹5 lakh | ₹17,500 |
| ₹15 lakh | ₹52,500 |
| ₹30 lakh | ₹1,05,000 |
| ₹50 lakh | ₹1,75,000 |
These figures are illustrative, based on one assumed yield, not a promised return, and actual dividend yields vary by stock, sector, and year depending on company profitability. Stock Charcha’s rule of 72 is a useful quick tool for estimating how long it takes your invested capital itself to double at a given growth rate, separate from the dividend income it throws off along the way.
Our breakdown of the 50/30/20 rule is a reasonable starting point for figuring out how much of your monthly income you can realistically route toward building this kind of corpus in the first place, rather than guessing at a number.
Which Types of Stocks or Funds Actually Pay Reliable Dividends?
In my own portfolio, the consistent payers have mostly been PSU banks, PSU energy and mining companies, and a few large private FMCG names, sectors that are mature, generate steady cash flow, and don’t need to reinvest every rupee into expansion. This isn’t a recommendation to buy any specific stock, just an observation of where dividend consistency tends to cluster in the Indian market.
If picking individual stocks feels like more work than you want, dividend-focused or value-oriented mutual funds and ETFs pool several such companies together. Our guide on types of mutual funds is worth reading to understand where dividend-oriented funds fit among the broader categories, and ETF versus mutual funds is a useful comparison if you’re deciding between the two structures for this specific goal. Our own guide on mutual funds for beginners is worth reading first if fund categories themselves still feel unfamiliar, and which fund category has actually delivered higher returns historically is a useful companion comparison once you’re ready to pick one.
Is Dividend Yield Alone Enough to Judge a Stock?
No, and this was my most expensive early mistake. A stock showing an unusually high dividend yield, say 8-9%, against its sector average of 3-4%, is often a warning sign rather than a bargain. Sometimes it means the share price has fallen sharply (which mechanically pushes yield up) because the market expects the dividend itself to be cut soon.
I learned this after holding a company with a tempting 7% yield that slashed its payout the following year once earnings dropped. This approach only works as real passive income if you check the payout ratio (how much of profit is actually being paid out) and the company’s earnings trend, not the yield number in isolation. A payout ratio consistently above 80-90% leaves very little cushion if profits dip even slightly. What a share dividend actually represents in terms of your ownership stake is worth re-reading at this stage too, since a dividend is ultimately a distribution of real company cash, not a magic bonus disconnected from the business.
How Are Dividends Actually Taxed in India?
This is the part most beginner content glosses over, and it genuinely changes your real return. Since April 2020, dividends are taxed in the hands of the investor at your applicable income tax slab rate, not at a flat rate, and companies deduct TDS at 10% if your dividend income from a single company exceeds ₹5,000 in a financial year.
If you’re in the 30% tax bracket, a ₹1 lakh dividend payout effectively becomes ₹70,000 after tax, which meaningfully changes the capital-needed math from the earlier table. It’s worth checking the current income tax slab rates and TDS thresholds on the Income Tax Department’s official e-filing portal before you plan around any specific number, since these figures should be verified as of whichever year you’re reading this in.
Comparing a dividend-heavy approach against a pure growth one is also where understanding CAGR genuinely helps, since it lets you check whether the total return (price growth plus dividends) from a holding actually beats a simpler growth-only fund over the same stretch.
Dividend Stocks or SWP from Mutual Funds, Which Builds Passive Income Better?
I get asked this constantly, and the honest answer is that they solve the same problem differently. A Systematic Withdrawal Plan lets you redeem a fixed amount from a mutual fund at regular intervals, giving you control over exactly how much income you draw, regardless of whether the underlying companies declared a dividend that quarter.
Dividend-based passive income depends on companies actually declaring payouts, which isn’t assured even from historically reliable payers during a bad year. An SWP, by contrast, lets you decide your own withdrawal amount, though it also draws down your capital over time if your withdrawal rate exceeds your portfolio’s growth. Stock Charcha’s 4% withdrawal rule is a well-known framework for figuring out a sustainable SWP rate that shouldn’t erode your principal too quickly. Our piece on SIP versus lumpsum investing is worth pairing with this if you’re building the underlying corpus you’ll eventually draw an SWP from.
What Mistakes Did I Make Early On With Dividend Investing?
Chasing yield without checking the business was the big one, already covered above. The second was underestimating how long it takes to notice the income. In year one, my ₹340 felt like nothing. By year five, with consistent additions, my annual dividend income had crossed ₹22,000, still modest, but visibly compounding in a way that finally felt real.
The third mistake was ignoring diversification across sectors. I was overweight in PSU banking stocks at one point, and when that sector had a rough couple of years, my dividend income actually fell year-on-year, which defeated the entire point of treating it as dependable income. Stock Charcha’s 100-minus-age rule is a decent starting heuristic for how much of your overall portfolio should sit in equity (dividend-paying or otherwise) versus safer instruments at your particular life stage. This same concentration mistake comes up often enough in reader portfolios that it’s one of the patterns our common investing mistakes guide covers in more depth.
How Do You Actually Build a Dividend Portfolio Step by Step?
A reasonable sequence for dividend investing for passive income, based on how I’d approach it again:
- Open a demat and trading account if you don’t already have one, and make sure your emergency fund is separately funded first
- Start with a dividend-focused or value mutual fund rather than individual stocks, if you’re not yet comfortable reading a company’s financial statements
- If moving to individual stocks, screen for a consistent 5+ year dividend history, a payout ratio under 70-80%, and stable or growing earnings
- Diversify across at least 4-5 sectors so one bad year in one industry doesn’t wipe out your entire income stream
- Reinvest the dividends themselves in the early years rather than spending them, so the income compounds instead of staying flat
Stock Charcha’s personal finance planner is useful at this stage for checking whether the monthly amount you’re planning to allocate toward building this portfolio actually fits your broader cash flow, alongside your other goals. Our broader guide on building wealth over the long term ties this specific strategy back into a full financial plan rather than treating it as an isolated bet.
Does Dividend Investing Fit Every Life Stage?
Not equally. In your twenties and thirties, with a longer runway and higher risk tolerance, growth-oriented equity usually compounds your total wealth faster than a dividend-first strategy, since reinvested growth beats a cash payout you’re not yet relying on. Dividend investing for passive income tends to make more practical sense once you’re within 10-15 years of needing that income to actually supplement your cash flow, during a career break, approaching retirement, or alongside another income source like rental income.
That said, starting early and letting the dividend reinvestment compound quietly in the background costs you very little, even if the income itself isn’t meaningful yet. It’s a long runway you’re building, not a quick cash flow switch you flip overnight, and our guide on how to start investing is worth another look if you’re still deciding where this strategy fits inside your very first portfolio.
What Rule of Thumb Can You Use to Check If You’re On Track?
If your goal is a specific amount of annual passive income, work backward from a conservative 3-3.5% net yield assumption. For a round target like ₹1 crore corpus built specifically for this purpose, Stock Charcha’s 15-15-15 rule offers a quick sanity check on how a ₹15,000 monthly SIP at an assumed 15% growth rate over 15 years could get you there, which you could then gradually shift toward dividend-paying holdings as the goal approaches.
Before committing serious capital to this strategy, it’s also worth confirming your emergency fund covers 3-6 months of expenses separately, since dividend income, however reliable it looks on paper, shouldn’t be the thing standing between you and a sudden expense.
So Is Dividend Investing Actually Worth It for Passive Income?
For me, yes, but only once I stopped treating it like a shortcut. Seven years in, my dividend income now covers a genuinely useful chunk of a few recurring monthly bills, not because any single stock did something spectacular, but because I kept adding, kept diversifying, and stopped chasing yield numbers that looked too good on a screener.
This approach rewards patience more than any other quality, and it punishes the instinct to chase the highest number on a stock screener. If you’re starting today, the honest advice is to expect very little for the first couple of years and to judge the strategy on a five-to-ten-year horizon, not a quarterly one, and our guide on building wealth over the long term is worth keeping nearby for that broader horizon.
This article is general financial education from HMA Wealth, not personalised investment or tax advice. HMA Wealth is not a SEBI-registered investment adviser, equity and mutual fund investments are subject to market risk, and dividend amounts, tax rates, and TDS thresholds mentioned here can change, so verify current figures with your broker, the relevant fund house, or a SEBI-registered investment adviser before acting on them.
FAQs –
What is dividend investing for passive income in simple terms?
It means buying shares of companies with a consistent, multi-year history of paying and ideally growing dividends, and holding them specifically for that recurring cash payout rather than for price appreciation alone.
How much money do you need to start dividend investing for passive income?
There’s no minimum to start, but to generate meaningful income, say ₹1 lakh a year, you’d typically need around ₹25-30 lakh invested at a realistic 3-4% average dividend yield, before accounting for tax.
Is dividend investing for passive income better than a mutual fund SWP?
They solve the same problem differently. Dividends depend on companies actually declaring a payout, while an SWP lets you control your own withdrawal amount from a fund, though both carry their own risks around sustainability and capital erosion.
How are dividends taxed for someone doing dividend investing for passive income in India?
Dividends are taxed at your applicable income tax slab rate, with companies deducting 10% TDS if your dividend income from a single company crosses ₹5,000 in a financial year, so actual current rates should be checked on the Income Tax Department’s portal.
Is a high dividend yield always a good sign when picking stocks?
Not necessarily. An unusually high yield compared to a sector average can signal that the share price has fallen because the market expects a dividend cut, so checking the payout ratio and earnings trend matters more than the yield number alone.