Last updated:
HMA Wealth may earn a commission if you sign up through some links on this page. This does not affect our recommendations. See our Disclaimer for details.
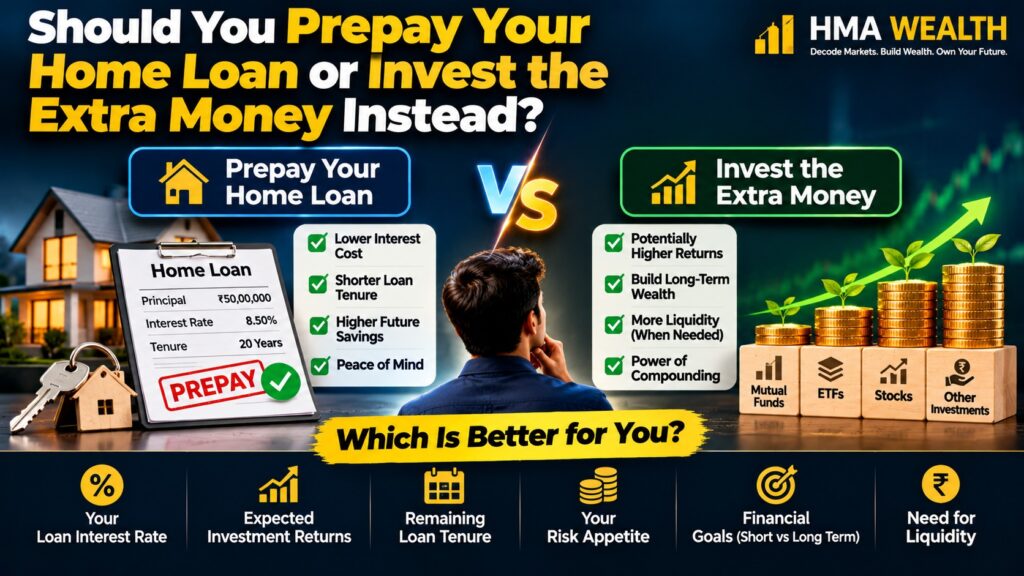
Table of Contents
Should You Prepay Your Home Loan or Invest the Extra Money Instead?
Two Diwalis ago I got a ₹3 lakh bonus and spent an entire weekend going back and forth with a spreadsheet open in one tab and my bank’s loan account in another. My home loan had about 14 years left on it at roughly 9% interest. My equity mutual fund SIP had been averaging a decent run over the previous few years. Every well-meaning relative had a different opinion, and none of them had actually run the numbers.
I ended up splitting it, which I’ll get to later. But the exercise taught me something most generic articles on this topic skip: the choice to prepay home loan or invest isn’t really a math question with one universal answer. It’s a math question with a personal-finance filter sitting on top of it, and the filter matters as much as the arithmetic.
This is exactly the kind of decision HMA Wealth spends time on, not because there’s a single “correct” answer to sell you, but because the framework for thinking it through is reusable for almost any extra-money decision you’ll face. If you’re still building your base knowledge of how investing accounts even work, our guide on how to start investing is worth reading alongside this one.
Why Does This Dilemma Even Exist in the First Place?
Because both options genuinely make sense on paper, and that’s precisely what makes this confusing. A home loan is debt, and clearing debt early feels responsible. Investing feels like putting your money to work for growth instead of letting it just erase a liability.
The question of whether to prepay home loan or invest the surplus only shows up when you have money beyond your EMI and emergency fund, a bonus, an increment, a maturing FD, or a windfall. If every rupee is already accounted for in your monthly budget, there’s nothing to decide. It’s the surplus that creates the question, and every home loan prepayment vs investment decision I’ve seen among friends and readers starts at exactly this point.
What’s the Actual Math Question Hiding Behind This Decision?
Strip away the emotion and the decision to prepay home loan or invest comes down to one comparison: is your home loan’s interest rate higher or lower than the return you can realistically expect from investing that same money over the same period?
If your loan costs you more in interest than your investment is likely to earn, prepaying wins mathematically. If your expected investment return is meaningfully higher than your loan rate, investing wins mathematically. The tricky part is that “likely” and “expected” are doing a lot of work in that sentence, because investment returns aren’t fixed the way a loan’s interest cost is.
How Do You Actually Compare a Loan Rate Against a Market Return?
A home loan’s interest rate is a known, contractual number. As of October 2026, floating home loan rates for salaried borrowers with good credit scores are broadly sitting in the 8–9.5% range across most major lenders, though this moves with the RBI’s policy rate, so it’s worth checking your own loan statement and the RBI’s official site for the current repo rate before you run your own numbers.
Equity mutual funds, by contrast, don’t have a fixed number. Over long stretches, say 10-15 years, broad equity index funds in India have historically delivered annualised returns that most financial planners model somewhere in the 10-12% range, but that figure is a historical average, not a promise, and any single 5-7 year window can land well below or above it. You can check a specific fund’s actual historical performance on AMFI’s website before assuming any number applies to your situation.
So the comparison isn’t “9% loan vs a certain 12% return.” It’s “9% fixed, contractual cost vs a historically-informed return that isn’t fixed and could disappoint you in a bad stretch.” That asymmetry is the whole reason the prepay home loan or invest decision deserves more thought than a one-line rule of thumb.
What Does This Actually Look Like With Real Numbers?
Let’s put the prepay home loan or invest comparison in rupee terms. Say you have a ₹5 lakh home loan prepayment amount sitting with you, 10 years remaining on a ₹40 lakh loan at 9% interest.
| Option | What happens |
|---|---|
| Prepay ₹5 lakh now | Loan tenure shortens by roughly 2-3 years, or EMI drops if you choose that route instead. You save the 9% interest you would have paid on that ₹5 lakh for the remaining years. |
| Invest ₹5 lakh in an equity SIP/lumpsum | If it grows at an illustrative 11% annualised average over 10 years, it could become roughly ₹14-14.5 lakh, though this is a projection based on one assumed rate, not a promised outcome. |
On paper, investing looks better because 11% beats 9%. But that 11% carries market risk your loan’s 9% simply doesn’t, and that gap between the two rates (roughly 2 percentage points in this example) is often not wide enough to comfortably justify taking on investment risk if you’re someone who loses sleep over EMIs. If the gap were 5-6 percentage points instead, the case for investing would be a lot stronger.
I ran a version of my own numbers through Stock Charcha’s rule of 72 just to sanity-check how long my invested amount would take to double at different assumed rates, and it was a useful gut-check before committing either way.
Does the Remaining Loan Tenure Actually Change the Answer?
Yes, and this is the part most people miss when they try to prepay home loan or invest decisions using only the headline interest-rate comparison. Home loan EMIs are structured so that the early years are interest-heavy and the later years are principal-heavy. Prepaying in year 2 of a 20-year loan saves you far more interest than prepaying in year 17 of the same loan, because you’re wiping out principal while interest is still accruing on a large outstanding balance.
| Years remaining on loan | Prepayment impact |
|---|---|
| Early (first 5-7 years) | High interest savings, strongly favors prepayment if rate gap is small |
| Middle (8-15 years) | Moderate savings, genuinely close call depending on rate gap |
| Late (last 3-5 years) | Low interest savings left to capture, investing often makes more sense |
If you’re early in your loan tenure, prepayment tends to carry more weight than the raw interest-rate comparison alone suggests, simply because of how amortisation works. The EMI tenure interest savings table above is exactly why timing inside your loan matters as much as the rate comparison itself.
What About the Tax Deductions You’d Be Giving Up?
This is the part people genuinely forget, and it changes the math meaningfully. The Section 24(b) deduction lets you claim up to ₹2 lakh a year on home loan interest for a self-occupied property, and under Section 80C, principal repayment (along with other eligible investments) is deductible up to ₹1.5 lakh a year, under the old tax regime. If you prepay aggressively and your loan closes early, you lose access to this loan prepayment tax benefit for the remaining years you would have otherwise had it.
Exact eligibility depends on which tax regime you’ve opted for and your total 80C utilisation from other instruments like PPF or ELSS, so it’s worth checking the specifics on the Income Tax Department’s official site rather than assuming your situation matches a generic example. Our explainer on the 50/30/20 rule is a reasonable place to start if you’re trying to figure out how much surplus you even have to allocate between tax-saving instruments, prepayment, and investing in the first place.
Does Your Risk Appetite Actually Matter More Than the Math?
In my experience, yes, more than most people want to admit. I know two colleagues with near-identical loan and income profiles who made opposite choices, one prepaid aggressively, one invested the surplus, and both are comfortable with their decision years later. Neither was wrong. What differed was how each of them slept at night.
If market volatility genuinely stresses you out, or if your job isn’t particularly secure, the certain, risk-free “return” of prepayment (you’re not paying 9% interest on money you no longer owe) has a value beyond pure numbers. It’s peace of mind you can actually bank on. This exact pattern, people chasing the mathematically optimal choice while ignoring whether it actually fits their temperament, is something HMA Wealth sees often enough in reader questions to flag on its own.
Are There Charges or Costs You Should Factor Into Prepayment?
RBI regulations prohibit banks from charging prepayment penalties on floating-rate home loans taken by individual borrowers, which is genuinely good news if your loan is floating-rate. If you’re on a fixed-rate loan, or if it’s a loan taken for a non-residential property, prepayment charges can still apply, typically 2-4% of the prepaid amount, so check your loan agreement or your bank’s official rate card before assuming it’s free. NBFCs and banks are required to disclose this clearly, but it’s genuinely worth a five-minute call to your loan officer to confirm before you transfer a lump sum.
Is There a Middle Path That Doesn’t Force an Either-Or Choice?
This is what I ended up doing with that ₹3 lakh bonus, and it’s honestly the approach HMA Wealth tends to recommend to most readers who write in with this exact dilemma. Split it. I prepaid ₹1.5 lakh against the loan and invested the remaining ₹1.5 lakh in an existing equity SIP top-up.
You don’t have to pick a side entirely. A reasonable rule many planners use: if the gap between your loan rate and your realistic expected investment return is under 2-3 percentage points, lean toward a 50-50 or 60-40 split rather than going all-in on either option. It reduces regret either way, and regret is a real cost even if it doesn’t show up on a spreadsheet.
Our guide on SIP versus lumpsum investing is worth reading if you’re leaning toward the investing side of the split and deciding how to actually deploy that money.
What Quick Rule of Thumb Can You Use If You Don’t Want to Build a Spreadsheet?
A reasonably sound shortcut for the prepay home loan or invest call: if your home loan interest rate is above 9-9.5%, lean toward prepayment, since that’s a fairly high fixed cost to be carrying. If it’s below 8% (common on older loans sanctioned when rates were lower, or on loans with a strong credit-linked subsidy), leaning toward investing becomes easier to justify, since the rate gap against historical equity returns is wider.
Before applying any rule of thumb, it’s worth checking Stock Charcha’s EMI-should-not-exceed-40%-of-income rule to confirm your EMI isn’t already eating an uncomfortable share of your take-home pay, because if it is, prepayment to bring that ratio down safely has value beyond the pure interest-rate math. And if investing is the direction you’re leaning, their note on the 15-15-15 rule is a fast way to sanity-check what a monthly SIP of that surplus could realistically grow into over a comparable timeframe.
What Should You Actually Check Before You Decide?
A short list worth going through before you transfer any lump sum, prepayment or investment:
- Confirm whether your loan is floating or fixed rate, and whether prepayment charges apply
- Check how many years remain on your loan, since early-tenure prepayment saves more interest
- Pull up your actual loan rate and compare it honestly against a fund’s real historical return, not an assumed number
- Make sure your emergency fund (ideally 3-6 months of expenses) is intact before you use surplus money for either option
- Factor in the 24(b) and 80C deductions you’d be giving up if the loan closes early
- Be honest with yourself about how much market volatility you can actually tolerate without losing sleep
If several of these point in different directions, that’s usually a sign the split approach is the more sensible one rather than a forced either-or call.
So What Actually Happened With My Own Decision?
The ₹1.5 lakh I prepaid shaved a little over a year off my remaining tenure. The ₹1.5 lakh I invested has had a mixed run since, up meaningfully in some years, flat in others, which is exactly the kind of outcome that would have stressed me out if I’d put the full ₹3 lakh into the market. Looking back, I don’t think either pure strategy would have left me better off by much. What I gained was not having to guess which direction interest rates or markets would move next, because I’d already hedged both ways.
That’s really the honest takeaway here. Whether you prepay home loan or invest the surplus isn’t a decision with a universally correct answer, and anyone promising you one is skipping past the risk side of the equation. Run your own numbers, check your own loan’s actual terms, and decide based on your own tolerance for carrying debt versus carrying market risk, not on what worked for a relative or a colleague whose situation only looks similar to yours on the surface.
This article is general financial education from HMA Wealth, not personalised investment or tax advice. Home loan rates, tax deduction limits, and historical fund returns mentioned here should be verified against current official sources, your loan statement, and a SEBI-registered investment adviser or qualified tax professional, as of the date you’re reading this, since all three can and do change. Mutual fund investments are subject to market risk, and any return figures above are illustrative projections, not promised outcomes.
FAQs — Should You Prepay Your Home Loan or Invest the Extra Money Instead?
Is it better to prepay a home loan or invest, in simple terms?
It depends on the gap between your loan’s interest rate and your realistic expected investment return. If your loan rate is above 9-9.5%, prepayment often makes more sense; if it’s meaningfully lower, investing has a stronger case, though market returns are never guaranteed the way loan interest is.
Does prepaying a home loan save more if done early in the tenure?
Yes. Home loan EMIs are interest-heavy in the early years and principal-heavy later, so prepaying in the first 5-7 years saves considerably more interest than prepaying in the last few years of the same loan.
Are there penalties for prepaying a home loan in India?
RBI rules prohibit prepayment penalties on floating-rate home loans taken by individuals. Fixed-rate loans or loans on non-residential property can still carry charges, typically 2-4% of the prepaid amount, so check your specific loan agreement first.
Do you lose tax benefits if you prepay your home loan or invest instead and close the loan early?
Yes, closing a loan early means losing access to Section 24(b) interest deduction (up to ₹2 lakh a year) and the 80C principal deduction (up to ₹1.5 lakh a year, under the old tax regime) for the remaining years you would have otherwise claimed them.
Can you split the money between prepaying a home loan and investing instead of choosing one?
Yes, and it’s a reasonable approach when the rate gap between your loan and expected investment returns is narrow, under 2-3 percentage points. A 50-50 or 60-40 split reduces regret either way compared to committing the full amount to one option.